
Many self-employed individuals must arrange their own health coverage rather than relying on an employer-sponsored plan. This often means evaluating different policy structures, cost-sharing arrangements, and provider networks to find coverage that aligns with personal health needs and business cash flow. Coverage options can include individual or family policies purchased directly from insurers or through a regulated marketplace, as well as account-based approaches that pair a high-deductible policy with a tax-advantaged savings account. Understanding these options helps sole proprietors weigh routine care access, financial exposure for major events, and portability when work circumstances change.
Key plan distinctions commonly involve how providers are accessed, which services are covered, and how costs are shared between insurer and enrollee. Network-based plans may limit provider choice but often reduce out-of-pocket costs for in-network care. More flexible networks can increase choice at higher cost. Other considerations include whether prescription drugs and preventive services are covered at low or no cost, and whether supplemental benefits such as dental or vision are available. For a sole proprietor, balancing monthly premiums against potential deductibles and out-of-pocket maximums typically informs practical selection.
Comparing plan categories may involve assessing typical premium ranges relative to expected health needs. For example, plans with lower monthly premiums can carry higher deductibles and greater cost exposure for hospital care, while richer plans may have higher premiums but lower cost at the point of service. Sole proprietors often track annual health spending to model whether lower premiums plus higher out-of-pocket risk or higher premiums with lower cost-sharing better aligns with their personal cash flow. Cost modeling may involve sample scenarios such as a routine outpatient year versus a year with a hospitalization.
Provider network considerations influence access and continuity of care. Network size, whether primary care referrals are required, and policies on out-of-network reimbursement may affect both convenience and cost. A narrow network plan can reduce premium levels but may limit choice if a specialist or particular facility is preferred. Conversely, broader networks may increase premium expense but offer more provider options. Many plans publish provider directories and explanation of benefits documents that may be reviewed to estimate likely in-network providers for common services.
Prescription drug coverage and preventive care rules commonly differ by plan and can materially affect annual costs. Some plans include tiered formularies that place medications on different cost tiers; others may require prior authorization for certain drug classes. Preventive services may be covered with little or no cost-sharing under many regulations, but coverage specifics can vary by insurer and policy. Sole proprietors may review formulary lists and preventive service provisions to anticipate routine medication expenses and screening costs when comparing options.
Tax and savings features can alter the effective cost of coverage. An HSA paired with an eligible high-deductible plan may allow pre-tax contributions and tax-free withdrawals for qualified medical expenses, potentially reducing net healthcare expense over time. Other tax-advantaged arrangements or credits may be available in some jurisdictions to offset premiums, depending on income and eligibility rules. It can be useful to consider how these mechanisms interact with personal income patterns and projected healthcare use when evaluating plan affordability.
To summarize, independent workers typically choose among several plan architectures that trade monthly premium levels against deductibles, network access, and ancillary benefits. Evaluating actual expected use, provider access needs, and potential tax-advantaged savings tools may clarify which plan attributes align with financial and care priorities. The next sections examine practical components and considerations in more detail.
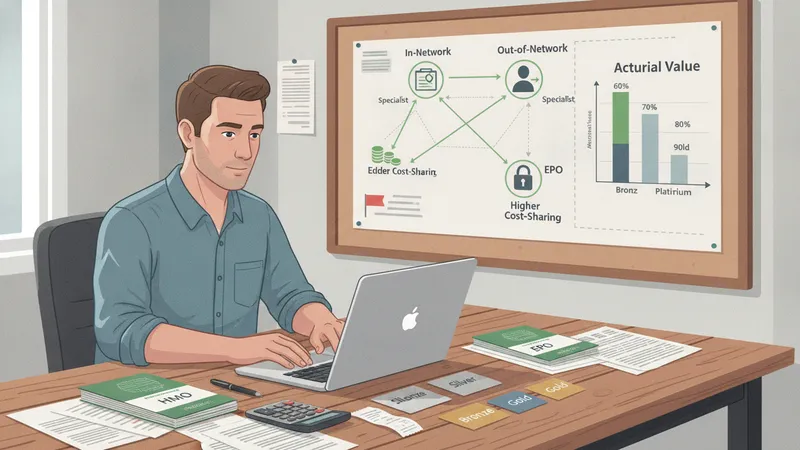
Managed care models represent the most common broad categories and can shape both access and cost-sharing. Health maintenance organization (HMO) models typically require members to select a primary care clinician to coordinate care and provide referrals for specialists; these plans can restrict out-of-network benefits. Preferred provider organization (PPO) designs often allow direct access to specialists and out-of-network providers but may impose higher cost-sharing for those choices. Exclusive provider organization (EPO) plans generally require use of an in-network provider list with fewer or no out-of-network benefits. Each category may be offered in multiple cost-sharing tiers.
Individual market plans sold through public exchanges or directly by insurers commonly come in metal tiers or alternative structures reflecting different actuarial values. Tiers usually indicate the percentage of expected costs the plan covers versus the enrollee’s share, which can help sole proprietors estimate typical annual expense under routine and higher-use scenarios. Some markets also offer catastrophic or limited-duration options subject to eligibility and regulatory conditions; these options often have different coverage rules and may restrict certain benefits, especially for routine care.
Association plans, professional group arrangements, or association health arrangements are sometimes available to independent workers through trade or professional organizations. These models can provide a grouping mechanism to negotiate terms, but regulatory frameworks vary by jurisdiction and may affect consumer protections and coverage guarantees. When considering such arrangements, sole proprietors may review the legal structure, whether coverage is fully insured or self-funded, and the protections that apply under relevant consumer protection laws.
Supplemental and ancillary coverage may include dental, vision, short-term disability, or critical illness riders that can be added to primary medical coverage or purchased separately. These options may address gaps in routine care access or income protection during temporary disability but can add to monthly cost. Sole proprietors often consider whether separate savings mechanisms or tailored ancillary products better match their anticipated needs versus bundled add-ons, keeping in mind differences in exclusions, waiting periods, and claim processes.
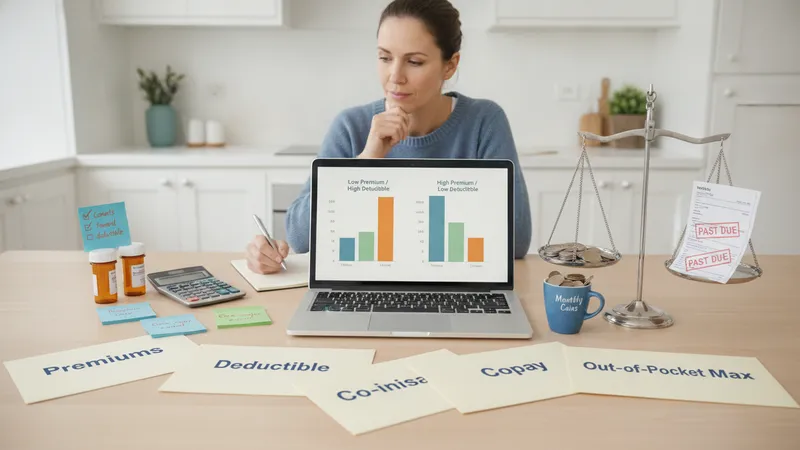
Monthly premiums represent the recurring payment for maintaining coverage, while deductibles, co-insurance, copayments, and out-of-pocket maximums define financial exposure when care is used. Plans that lower monthly premiums may increase deductible amounts and co-insurance percentages. Conversely, plans with higher premiums often reduce point-of-service costs. To evaluate trade-offs, sole proprietors may estimate annual utilization scenarios—such as minimal routine care versus one major event—to compare likely total spending under different plan designs. This scenario-based approach can illuminate which cost structure aligns with personal financial tolerance.
Out-of-pocket maximums limit total annual spending for covered services and may be a key metric for those concerned about catastrophic risk. Many policies set separate maximums for in-network versus combined in- and out-of-network services. Deductible design may include embedded or family-aggregate structures for family coverage. Understanding how deductibles apply to different service categories—such as whether prescriptions count toward the medical deductible or have separate tiers—can materially affect projected yearly costs for those who rely on regular medications or frequent outpatient care.
Premium subsidies, tax credits, or income-based assistance may be available in certain regulatory environments and can alter effective monthly cost for eligible individuals. Eligibility for these programs typically depends on household income relative to local thresholds and may require enrollment through designated marketplaces. Sole proprietors who experience variable income across years may find subsidy eligibility changes from one year to the next; forecasting income and understanding the reporting process for any assistance program are practical considerations when estimating net premium expenses.
Cost estimation can also incorporate potential savings arrangements like health savings accounts or flexible spending accounts where available. Contributions to certain accounts may be pre-tax or tax-advantaged and can be used for qualified medical costs, reducing net outlays. The interaction between these accounts and plan types (for example, HSAs typically require a qualifying high-deductible plan) should be verified against plan eligibility rules and tax regulations. Treat these arrangements as part of a broader budgeting strategy rather than a guaranteed cost reduction.
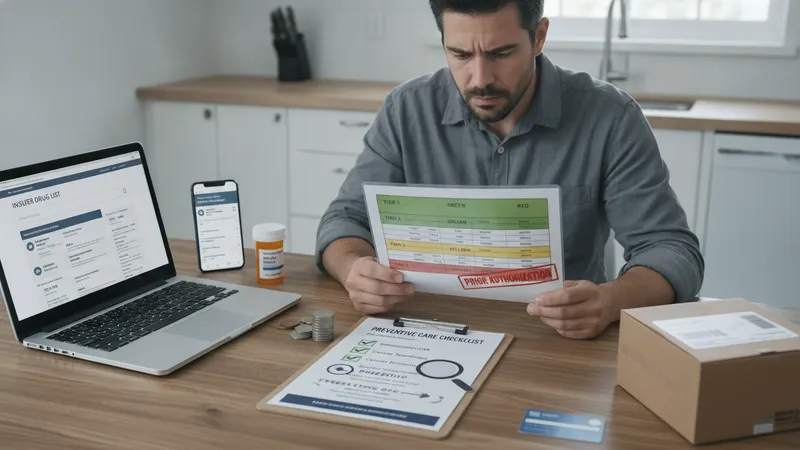
Prescription drug coverage frequently uses formulary lists and tiered copayment or co-insurance structures that affect out-of-pocket medication costs. Some plans require prior authorization or step therapy for specific drug classes, which can delay access or require documentation from a prescriber. Sole proprietors who depend on ongoing medications may review sample drug lists to estimate recurring costs and consider whether generic alternatives or mail-order options are permitted and how those channels alter pricing and convenience for chronic therapies.
Preventive services are commonly designated to receive lower cost-sharing in many regulatory frameworks, often covering immunizations, screenings, and certain counseling without a deductible. However, the exact preventive benefit set may vary by plan and jurisdiction, and exceptions can apply for services tied to diagnostic or treatment contexts. Verifying which preventive services are included and whether coding or billing practices can shift services from preventive to diagnostic categories may affect expected out-of-pocket expense for routine care and screenings.
Network adequacy and provider availability can influence continuity of care and travel time to preferred clinicians or facilities. Some plans publish provider-to-member ratios or network size statistics to indicate network breadth. Narrower networks may reduce premiums but could require changing clinicians to remain in-network. When continuity with a specialist or facility is important, checking provider directories and confirming network status for key clinicians often provides clarity before selecting a plan. Be aware that directories may lag behind real-time changes, so verification with the provider is a common consideration.
Telehealth and virtual care options are increasingly included in plan benefit designs and can alter access patterns for routine care. These services may offer lower per-visit costs and greater scheduling flexibility, though coverage limits and eligible service types vary. For sole proprietors with geographically dispersed work patterns or limited local access, telehealth availability may affect the practical value of a plan. Review any constraints on telehealth benefits, such as geographic restrictions, covered visit types, and cost-sharing differentials.
Enrollment windows and special enrollment criteria commonly govern when individuals may begin or change coverage. Regular open enrollment periods typically occur on an annual schedule in many systems, while qualifying life events—such as changes in household composition or income—may trigger special enrollment rights. Sole proprietors who experience fluctuating personal circumstances may benefit from tracking these periods to avoid temporary gaps in coverage, understanding that requirements and timelines vary by jurisdiction and plan type.
Eligibility for specific plan types or financial assistance programs can depend on income, household size, age, or prior coverage status. Verifying documentation requirements and the definition of household income used by an eligibility program helps clarify potential subsidy availability. For individuals with variable income across the calendar year, estimating annualized earnings and understanding any reconciliation requirements for assistance programs can reduce unexpected liabilities or repayment obligations at year-end.
When comparing plans, relevant factors include expected annual cost under realistic use scenarios, provider network fit, prescription drug coverage alignment, preventive service provisions, and any tax-advantaged savings compatibility. Creating a matrix that lists these factors for each candidate plan can help compare trade-offs systematically. Include likely out-of-pocket totals under low-, medium-, and high-use scenarios rather than relying solely on monthly premium figures in isolation.
Documentation review and insurer communications are practical final steps before selection. Examine summary plan descriptions, benefit booklets, and claim appeal processes to understand limitations, exclusions, and complaint mechanisms. Consider how billing coordination, prior authorization processes, and customer service channels may affect the ease of obtaining care and resolving disputes. These operational factors often shape real-world experience with a policy and are worth including in any comprehensive comparison.