
Financial advisory services involve professional activities that help individuals and organizations clarify financial goals, analyze current resources, and develop plans to manage capital, risk, taxation, and future obligations. Practitioners in this field may provide structured financial planning, investment oversight, retirement income modelling, tax-aware strategies, and estate coordination. These activities typically combine quantitative analysis with client interviews to produce written plans, modelled scenarios, and ongoing monitoring schedules. The concept centers on matching a client’s objectives and constraints with appropriate financial frameworks, delivered through advisory tools, documented recommendations, and periodic reviews.
Different professional roles within the advisory field often focus on complementary functions. For example, some professionals concentrate on investment portfolio construction and rebalancing, while others emphasize long-range cash flow and retirement modelling or tax planning and estate documentation. Credentials, licensing, and compensation structures may vary and can influence the scope of services offered. Advisory work commonly requires familiarity with regulatory standards, recordkeeping practices, and disclosure obligations that frame how analysis and recommendations are presented to clients.
Comprehensive financial planning typically follows a multi-step framework: information gathering, goal setting, analysis, recommendations, implementation support, and periodic review. This framework may be applied by certified planners, registered advisers, or other regulated professionals, and it can be scaled depending on client complexity. The planning output often includes scenario testing such as sensitivity to market returns, longevity assumptions, and spending patterns. Planners commonly document assumptions and trade-offs so clients can compare alternatives without implying a single guaranteed result.
Investment management within advisory services often emphasizes asset allocation, diversification, cost awareness, and risk monitoring. Advisors may use passive funds, active managers, or a mix, and they often consider time horizon and liquidity needs when proposing allocations. Portfolio review practices typically include periodic rebalancing rules and performance monitoring against stated benchmarks. These measures can help keep portfolios aligned to objectives but do not ensure outcomes; they serve as organizational and risk-control tools within a broader plan.
Retirement income planning in advisory roles commonly addresses sequencing of withdrawals, potential longevity exposure, and coordination with public or employer-sponsored benefits. Planners may model expected retirement spending under multiple scenarios that vary assumptions about returns, inflation, and life expectancy. Tools used for this purpose can include deterministic projections and probabilistic simulations. The emphasis is usually on balancing income stability with preservation of capital, noting that trade-offs are inherent and subject to change over time.
Advisory work often intersects with tax and estate considerations, requiring collaboration with tax preparers and legal professionals when appropriate. Advisors frequently identify tax-efficiency opportunities such as asset location strategies, timing of distributions, or charitable giving mechanisms; these are typically presented as considerations with advantages and limitations. Estate-related tasks can include beneficiary reviews, coordination of wills and trusts, and liquidity planning for transfer costs. Such services commonly involve documentation and referrals rather than unilateral implementation by the advisor.
In summary, financial advisory services encompass a set of analytical and client-facing tasks that together aim to structure financial decisions across planning, investing, retirement, tax, and estate domains. Roles vary by specialization, credentials, and compensation model, and deliverables commonly include written plans, portfolio actions, and scheduled reviews. The next sections examine practical components and considerations in more detail.
Advisory practices can be categorized by the primary services they offer and professional credentials held by practitioners. Common categories include planners who focus on comprehensive, multi-topic plans; investment advisers who specialise in portfolio construction; and wealth managers who combine investment oversight with additional services such as tax coordination and trust administration. Credentials such as Certified Financial Planner (CFP) or Chartered Financial Analyst (CFA) often signal different training emphases. Regulatory registration or licensing may influence permissible activities and disclosure requirements. Clients typically select a model that aligns with the complexity of their financial situation and the level of ongoing interaction they expect.
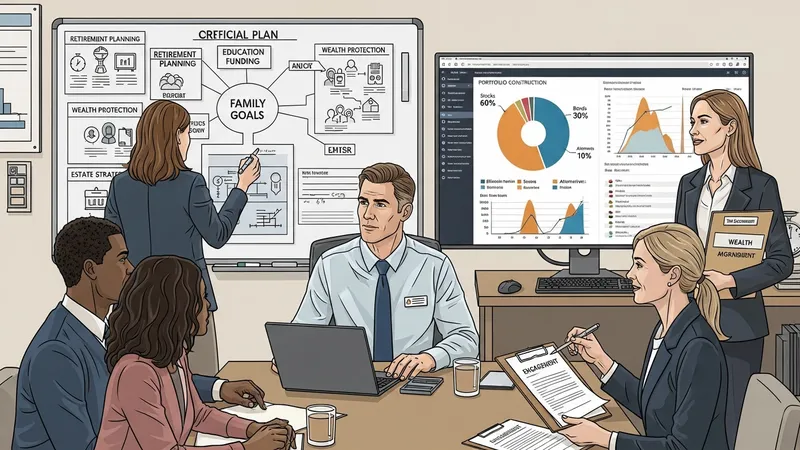
Compensation structures commonly fall into several patterns: asset-based fees, hourly billing, project or flat fees for planning engagements, and commission-based arrangements for certain product sales. Each structure may affect perceived conflicts of interest and the types of products or services most often proposed. For instance, asset-based fees may incentivize ongoing portfolio management, while flat planning fees may be used for one-time strategic reviews. Advisors and clients often discuss fee transparency and service scope as part of establishing an engagement agreement.
Professional roles also differ in implementation authority and scope. Some advisers provide recommendations and leave implementation to clients or third parties, while others offer discretionary authority to execute trades and rebalance portfolios on behalf of clients. Discretionary arrangements typically require clear written agreements and governance processes that specify limits, reporting intervals, and oversight mechanisms. The choice between advisory styles can affect operational workflows, tax considerations, and frequency of client communication.
Considerations for selecting a service model often include the client’s need for coordination across advisors, frequency of life events that affect planning, and preferences for ongoing monitoring versus episodic advice. In practice, multi-disciplinary teams may collaborate to combine tax, legal, and investment expertise. When evaluating roles, stakeholders commonly review credentials, sample engagement documents, and conflict disclosures to understand how recommendations will be developed and implemented.
Planning functions within advisory services commonly start with establishing objectives and constraints—time horizon, risk tolerance, liquidity needs, and major anticipated expenses. Advisors may employ cash-flow projections, scenario analysis, and stress testing to examine how objectives hold up under different market and life-event conditions. Investment guidance typically translates planning outputs into target asset allocations and tactical considerations. The planning output is often iterative: assumptions are refined as new information arises, and advisors may recommend periodic revisits to ensure alignment as circumstances change.
Investment guidance tasks often include risk profiling, selection of appropriate vehicles, attention to costs and tax efficiency, and explicit rebalancing rules. Asset allocation tends to account for diversification benefits across asset classes and geographies, while recognizing that historical correlations can shift over time. Many advisors present both strategic allocation (long-term targets) and tactical overlays (temporary deviations based on specific conditions), clarifying that tactical approaches add complexity and are not risk-free. Documentation of rationale and monitoring schedules is a common control practice.
Retirement considerations commonly emphasize sequencing of withdrawals, required minimum distribution timing where applicable, and interaction with public or employer-provided benefits. Advisors may model replacement-rate targets (the percentage of pre-retirement spending that needs to be replaced) and evaluate sustainable withdrawal strategies under varying return assumptions. Longevity risk and health-care cost estimates are often incorporated as sensitivity inputs. These analyses typically inform whether a plan prioritizes income stability, capital preservation, or a balance of both.
When translating plans into action, advisors often identify implementation roadmaps that include prioritization of accounts, tax-aware distributions, and periodic re-evaluation triggers. Common practice is to set review intervals—annual or semiannual reviews are typical—where progress, assumptions, and potential changes to strategy are discussed. Such structured reviews help maintain alignment with objectives and provide documented checkpoints for adjusting recommendations as needed.
Risk management in advisory contexts often addresses both investment volatility and non-investment exposures such as income disruptions, illness, or property loss. Advisors may analyse insurance needs (life, disability, property) as part of a holistic risk assessment, outlining potential gaps and trade-offs. Risk mitigation tools commonly include diversification, hedging strategies, insurance arrangements, and cash reserves. These tools are typically presented as components of a broader plan rather than absolute protections, with attention to cost-effectiveness and the client’s tolerance for residual risk.
Tax considerations frequently influence portfolio construction and distribution strategies, particularly when multiple account types or jurisdictions are involved. Advisors may discuss asset location (placing income-generating assets in tax-favored accounts), timing of taxable events, and tax-loss harvesting as potential considerations. Collaboration with tax professionals is common for complex situations. The goal of tax-aware planning is typically to improve after-tax outcomes in a manner consistent with overall objectives, acknowledging that tax laws and interpretations can change over time.
Estate planning functions within advisory services generally focus on ensuring that a client’s wishes for wealth transfer, guardianship, and decision-making are documented and coordinated with financial accounts. Advisors often review beneficiary designations, liquidity needs for potential transfer taxes or settlement costs, and the alignment of designated trustees or executors with overall objectives. Where appropriate, advisors recommend consultation with qualified legal professionals to draft or update wills, trusts, and related instruments, presenting these as coordinated elements rather than standalone solutions.
Integration across risk, tax, and estate considerations is a common advisory practice because choices in one area often affect outcomes in others. For example, an asset allocation designed to limit volatility may change expected taxable distributions; an estate strategy involving trusts can affect liquidity needs and tax exposure. Advisors typically document interdependencies and present trade-offs so clients can weigh options with a clearer understanding of potential consequences under differing scenarios.
Operational practices in advisory firms commonly include client onboarding, documentation of objectives and constraints, compliance monitoring, and periodic performance reporting. Onboarding often involves disclosure of services, fee schedules, potential conflicts of interest, and a written engagement agreement. Firms may maintain formal policies for recordkeeping, confidentiality, and business continuity. Clear operational processes help ensure that advice is consistently applied and that review mechanisms exist to detect mismatches between stated objectives and implemented actions.
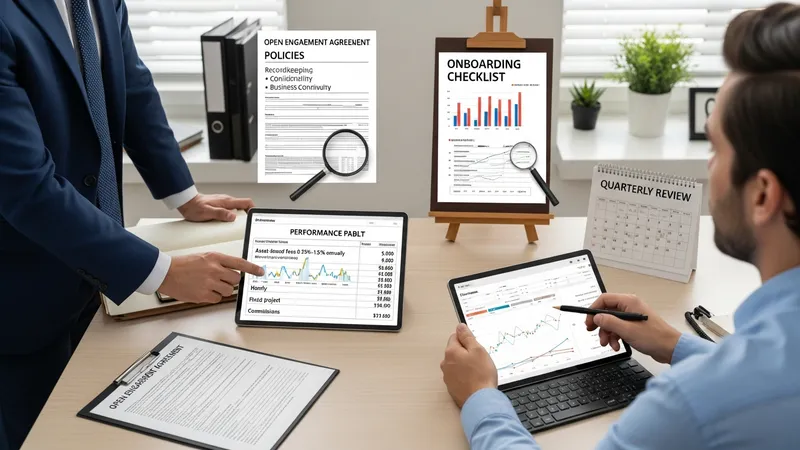
Fee structures vary and may include asset-based fees (a percentage of assets under management), hourly billing, fixed project fees, or commissions tied to specific products. Asset-based fees commonly range from approximately 0.25% to 1.5% annually in many markets, while hourly or flat planning fees can vary from modest amounts to several thousand in local currency depending on complexity. Each fee model has implications for perceived incentives and for the types of services prioritized; transparent disclosure of fees and services is a standard practice to support informed client decisions.
Review processes typically include scheduled portfolio and plan reviews—often annually or semiannually—with additional reviews triggered by major life events. Reviews generally reassess assumptions, measure progress toward goals, and document any changes to objectives or risk tolerance. Performance reporting may show returns relative to benchmarks, attribution analyses, and summaries of transactions. These reviews function as governance checkpoints to ensure continued relevance and to document rationale for any material adjustments.
Practical considerations for clients and advisers include maintaining clear communication channels, agreeing on measurable objectives, and setting realistic review cadences. Advisors often recommend establishing an emergency cash buffer and documenting succession plans for continuity of advice. Such considerations are offered as prudent planning practices rather than guarantees, and they are typically tailored to the client’s circumstances and preferences during the onboarding and review process.