
Business tax consultants are professionals who provide structured guidance to organizations on interpreting and applying tax laws. They typically analyze a business’s legal structure, transaction flows, and reporting obligations to identify relevant tax treatments. This role often involves translating statutory rules and administrative guidance into practical workflows, clarifying filing deadlines, and advising on documentation that supports specific tax positions. The objective of such guidance is informational: to help organizations understand how tax rules may apply to their operations and to reduce uncertainty in routine compliance tasks.
Consultants often combine technical tax knowledge with accounting and regulatory context. They may review prior returns, identify documentation gaps, and explain how specific rules interact with common business activities such as payroll, sales, acquisitions, or international transactions. Their inputs can include presenting options for recordkeeping formats, describing typical reporting lines, and outlining how different tax provisions could affect timing of income and deductible expenses. This information is presented as analysis and interpretation rather than prescriptive action.
Scheduled compliance reviews by CPAs or outsourced advisors may typically cover reconciliations between accounting records and tax bases. These reviews often examine how bookkeeping classifications affect taxable income, and they may highlight documentation that supports deductions or credits. In practice, such engagements can vary in frequency from quarterly to annual, depending on the business size and transaction volume. Advisors commonly aim to present a clear mapping between accounting entries and tax reporting lines so that internal staff can maintain consistent records for future filings and audits.
Tax attorneys are frequently engaged when legal interpretation or representation may be useful, for example in complex contract reviews, transfer-pricing arrangements, or litigation risk assessments. Their analysis generally focuses on statutory language, administrative guidance, and precedent from authoritative adjudications. In cases where a legal position has potential exposure, attorneys may outline likely arguments and the types of documentation that could support those positions, while avoiding promises about outcomes. Their role is informational and legal in nature rather than operational bookkeeping.
Outsourced advisory services can complement in-house accounting by delivering targeted research on specific transactions, such as business reorganizations or cross-border payments. These providers often supply written memos that summarize relevant rules, illustrative calculations, and suggested documentation protocols. Engagements may also include assistance with tax provision mechanics that feed into financial statements. Cost and scope typically vary by provider; the value provided is generally framed as context and clarification rather than guaranteed tax results.
Teams that combine CPA, legal, and outsourced advisory inputs may provide layered perspectives: accounting accuracy, legal interpretation, and implementation options. This multi-disciplinary approach can help organizations identify where internal processes may need adjustment to support tax reporting. For example, consistent classification of capital expenditures versus operating expenses can affect depreciation schedules and tax liabilities. Consultants typically explain these interactions and present options in neutral terms so that management can consider operational priorities alongside tax implications.
The next sections examine practical components and considerations in more detail.
Certified Public Accountant (CPA) tax advisory services often focus on reconciling financial records with tax reporting requirements and preparing or reviewing tax filings. A CPA may generate schedules that support income recognition, deductions, and tax provision entries used in financial statements. Tax attorneys provide legal interpretation and may assess the legal defensibility of tax positions or represent a client in administrative proceedings. Outsourced advisory firms can offer periodic compliance checks, research memos, and implementation support for particular transactions. Each provider type typically brings a different emphasis—accounting alignment, legal analysis, or operational implementation—so organizations may engage more than one type depending on complexity and risk.
When selecting the mix of services, organizations often consider factors such as transaction complexity, internal capacity, and existing documentation practices. For routine filings, a CPA-led approach that integrates with bookkeeping systems may suffice. For transactions with material legal questions—such as allocation of liabilities in restructurings—tax attorneys may be consulted to interpret statutes and case law. Outsourced advisors may be engaged for targeted projects where internal resources are limited. These arrangements are typically described in engagement letters that outline scope, deliverables, and fee arrangements in neutral terms.
Typical deliverables vary by service type and engagement length. CPAs may produce return drafts, reconciliation schedules, and checklists for recordkeeping; tax attorneys often provide legal memoranda and position analyses; outsourced advisors may deliver research notes and implementation checklists. The level of detail and format of documentation can influence internal processes, for example by clarifying what invoices or contracts should document a transaction. Organizations often treat these outputs as informational inputs that inform internal decision-making and controls rather than as directives.
Costs and timelines of engagements commonly depend on the volume of transactions, the degree of uncertainty, and the level of documentation review required. Short-term research memos may be completed in days to weeks, while comprehensive compliance reviews or transaction analyses may span months. Fee structures vary and may include hourly billing, fixed-fee projects, or retainer arrangements; firms typically describe these options without guaranteeing outcomes. Organizations often weigh these practical trade-offs when determining the appropriate level of external support.
Recordkeeping guidance from consultants often centers on documenting the facts and business purpose that support tax treatments. Advisors may describe which documents—contracts, receipts, time records, or invoices—typically substantiate particular deductions or classifications. They can also suggest formats for organizing records to streamline preparation of tax returns and facilitate responses to inquiries. Such recommendations are informational and intended to improve traceability between business activities and tax reporting lines, rather than to provide definitive legal protection in every circumstance.
For reporting, consultants typically explain how accounting classifications map to tax forms and schedules. This mapping can identify timing differences between book and tax income, depreciation bases, or tax-specific adjustments. Firms may prepare or review draft returns to ensure consistency with source records and to flag areas that may warrant additional documentation. These activities are framed as quality-control and interpretation services, which may reduce the likelihood of inadvertent reporting errors when implemented by internal teams.
Consultants may also outline common filing obligations and deadlines relevant to typical business operations, including periodic estimated payments and informational returns. They often emphasize the need for timely record retention and may advise on retention periods commonly cited in administrative guidance. This guidance generally reflects prevailing administrative practices and is presented to help organizations align internal calendars and workflows with external filing timelines, not as a schedule of mandatory actions imposed by the advisor.
Where electronic filing and digital recordkeeping are used, consultants can describe workflow adjustments that often streamline compliance. Examples include reconciling payroll systems to wage reporting, tagging transactions for tax categories, or maintaining audit trails for adjustments. Such process descriptions typically include pros and cons of different approaches and considerations for internal control, allowing management to evaluate which methods align with their accounting systems and operational constraints.
Strategic planning discussions with consultants often revolve around timing, classification, and documentation of transactions that affect taxable income. Advisors may describe how acceleration or deferral of income and expenses can change tax reporting periods and the potential impact on financial statements. They also typically explain common deduction categories—such as employee compensation, operating expenses, and capital expenditures—and the types of records that support each category. This information is designed to inform decision-making and to clarify documentation practices relevant to specific tax provisions.
Consultants frequently review documentation protocols that support deductible items, such as maintaining contemporaneous records for travel or business entertainment where relevant tax rules apply. They may provide templates or checklists that identify the key data points typically considered relevant by tax authorities. These materials aim to make it easier for internal staff to collect and retain evidence that aligns with standard administrative expectations. The intent is educational: to increase the reliability of deductions claimed based on available facts.
When multiple tax treatments are possible, consultants may present comparative analyses that describe potential tax consequences under different classifications. For example, they might outline how treating a payment as capital expenditure versus repair expense can affect depreciation schedules and current-year deductions. Such analyses are framed quantitatively where possible and typically include assumptions, so readers can assess which factors most influence the results. This approach helps organizations weigh accounting and tax trade-offs within their operational context.
Consultants often highlight record retention timelines and indexes that help locate supporting documents if needed later. They may describe how consistent classification in accounting systems reduces ambiguity and simplifies subsequent tax reporting or audits. These procedural recommendations typically aim to integrate tax documentation needs into regular operational routines so that reporting teams have the materials required to substantiate positions without relying on ad hoc reconstruction of facts.
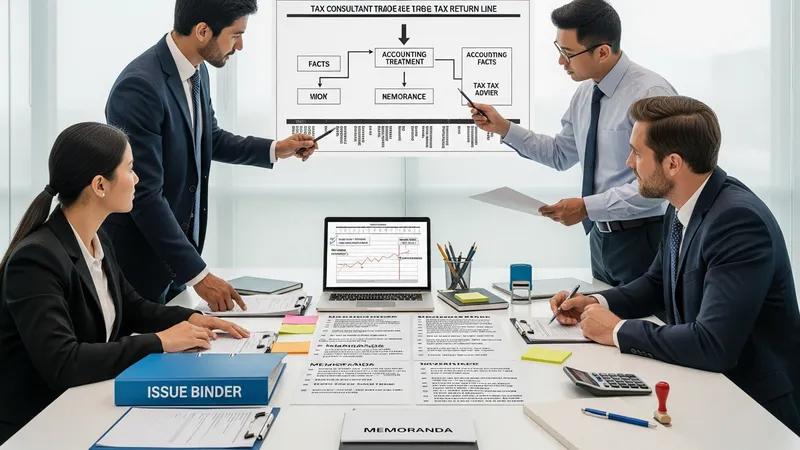
Audit preparedness advice from tax consultants commonly includes organizing documentation, preparing clear explanations of transactions, and outlining typical evidence that may be requested by examiners. Consultants may help compile issue-specific binders or memoranda that trace a position from the underlying facts through the accounting treatment to the tax return line. This preparation is informational and intended to facilitate clear responses if an inquiry occurs, rather than to predict outcomes of any examination.
Representation in dispute situations is generally provided by attorneys or experienced tax professionals who can interact with authorities on factual and legal matters. Consultants may explain the roles that different professionals play during administrative reviews, such as who typically handles factual explanations versus legal argumentation. They may also describe typical timelines and stages of an inquiry so organizations can understand procedural expectations and plan internal resource allocation accordingly.
Ongoing engagement models vary and can include periodic compliance reviews, annual health checks of tax positions, or retainer arrangements for ad hoc research. Such models often aim to maintain continuity of institutional knowledge and to ensure documentation is current. Consultants typically describe the administrative mechanics of these arrangements—reporting cadence, deliverable types, and communication protocols—so organizations can evaluate how external support might fit into existing governance structures without implying that any specific arrangement is required.
Cost factors and resource considerations for ongoing relationships commonly include the complexity of transactions, volume of filings, and the in-house team’s capacity. Advisors often outline how these variables influence engagement scope and estimated time commitments. Descriptions of cost structures are usually presented as ranges or typical patterns rather than fixed prices, enabling organizations to consider resource planning and internal cost-benefit analysis in an informational manner.